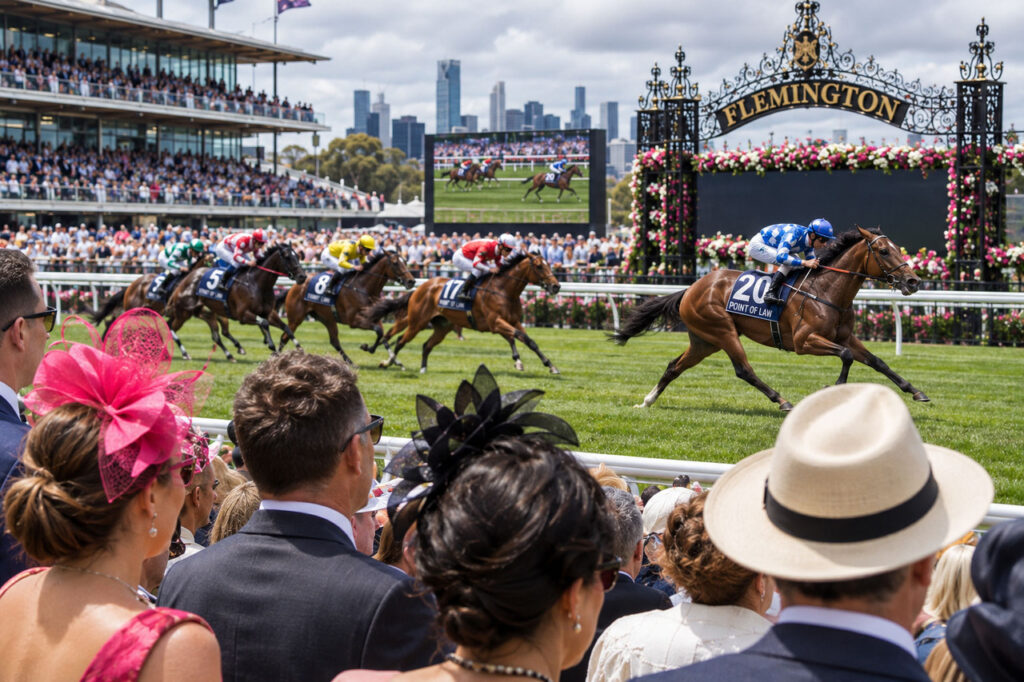
Yesterday’s celebrations came with a particularly unwelcome announcement, as the Reserve Bank lifted interest rates another 0.25%, taking the official cash rate to 4.85%. It’s the fifth increase this year, pushing borrowing costs to levels not seen since the global financial crisis in 2008.
For Australian households already juggling expensive groceries, fuel, electricity, insurance and housing, the timing couldn’t be much worse. Christmas is now just weeks away, and rather than planning holidays or spending a little extra on family celebrations, many mortgage holders will be calculating how much more of their income needs to go towards keeping a roof over their heads.
The latest increase adds approximately $83 a month in interest to a $400,000 mortgage, assuming the full rate rise is passed on. For a household carrying $800,000 in debt, that’s another $167 each month, on top of the cumulative increases already delivered throughout 2026.
But there’s another question worth asking. Are we reaching a point where the Reserve Bank’s efforts to contain inflation are themselves contributing to some of the financial pressures Australians are experiencing?
Interestingly, mortgage interest payments aren’t included in Australia’s Consumer Price Index, the primary measure used to track inflation. Housing still represents a substantial component of the index, however, including rents, new home construction, council rates and household utilities. So while a rate increase doesn’t directly push up the CPI through mortgage repayments, it can influence other costs throughout the economy.
Landlords facing higher financing costs may seek increased rents, while developers and builders dealing with more expensive borrowing can face additional pressure on construction activity. These effects aren’t automatic, and weaker demand can work in the opposite direction, but they highlight the difficulty of using interest rates alone to manage inflation when housing supply remains constrained.
The RBA’s argument is that allowing inflation to remain elevated would ultimately do more damage, eroding purchasing power and potentially requiring even harsher measures later. It’s a reasonable concern, although households experiencing the immediate financial consequences may understandably question how much more pressure they can absorb.
With the Australian economy slowing, housing prices weakening and unemployment rising, the risk is that consumers continue to pull back on spending while the cost of essential goods and services remains stubbornly high. That combination is particularly uncomfortable for retailers and small businesses heading into what should be their busiest trading period.
For precious metals investors, this environment also deserves attention. Higher interest rates can place pressure on gold, which produces no interest income, but slowing economic growth, uncertainty around financial markets and concerns about longer-term inflation can encourage investors to reconsider defensive assets.
The Melbourne Cup might still stop the nation for a few minutes each November, but Australia’s economic problems aren’t taking the afternoon off. With Christmas approaching and another rate rise now filtering through the economy, many Australians will be hoping the Reserve Bank has finally done enough.
Australia’s Consumer Price Index measures changes in the prices of goods and services, rather than every expense households face. Mortgage interest is deliberately excluded because including it would create a direct feedback loop: the RBA raises interest rates, mortgage interest costs rise, measured inflation increases, and the RBA potentially responds by raising rates again.
Instead, the ABS publishes separate Selected Living Cost Indexes that include mortgage interest charges and better reflect the financial experience of different household groups.
This distinction matters because inflation can be falling while the actual cost of living for mortgage holders continues to rise. It also explains why official economic figures don’t always reflect the financial pressure being experienced around the kitchen table.
Disclosure: This article is provided for general information and educational purposes only and does not constitute financial advice. Markets can move quickly and past performance is not a reliable indicator of future results. Always conduct your own research and consider your personal circumstances before making investment decisions.