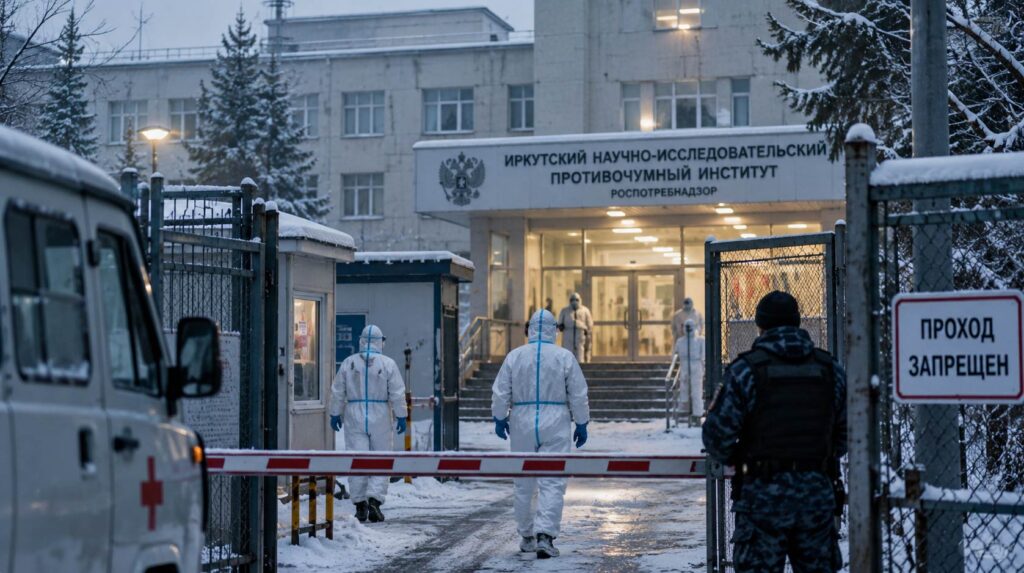
A health scare emerging from Russia has attracted international attention this week after a worker at an anti-plague research institute in Siberia died from pneumonia of an unknown origin, prompting quarantines and testing of those who had been in contact with her. Russian authorities have since reported no confirmed plague cases among those contacts, and international health authorities currently consider the wider risk low, but it has not taken much for memories of early 2020 to come flooding back.
That reaction is understandable because the world is still dealing with many of the economic consequences left behind by COVID. Australia managed to protect households and businesses through lockdowns with enormous government support, ultra-low interest rates and widespread financial assistance, but those measures came at a cost. Government debt increased sharply, monetary conditions became extraordinarily loose and, as the economy reopened, inflation eventually became the problem central banks have spent years trying to contain.
Australia today would enter another major health crisis from a very different position. Households are already dealing with substantially higher mortgage repayments, elevated living costs and another tightening cycle from the RBA, while governments have less comfortable balance sheets than they did entering 2020. Another extended shutdown could once again require income support, business assistance and significant government borrowing at precisely the time policymakers are trying to reduce inflationary pressure rather than create more of it.
This is where the comparison with gold becomes particularly interesting. Gold did not simply rise during COVID because people were frightened; in fact, like many assets, it initially came under pressure as investors scrambled for cash. The stronger move came as governments and central banks responded with enormous stimulus programs, near-zero interest rates, rapidly expanding debt and unprecedented amounts of liquidity flowing through financial markets.
Another serious pandemic would potentially create the same policy dilemma, but from a much higher starting point for both debt and gold. If economic activity were severely restricted again, governments would face pressure to support households and businesses while central banks could eventually be forced to loosen monetary conditions. At the same time, disrupting production, transport and global supply chains could create exactly the kind of inflationary pressures policymakers have spent the past several years trying to bring under control.
For Australian households, another lockdown could therefore be considerably more difficult than the first. The mortgage that cost relatively little to service during the ultra-low-rate environment of 2020 and 2021 is now considerably more expensive, household savings buffers have been eroded by years of higher prices, and government support would potentially need to be funded through even greater borrowing.
None of this means the current situation in Russia is developing into another COVID. There is presently no evidence of a widespread plague outbreak, modern antibiotics can successfully treat plague when detected early, and health authorities are closely monitoring the situation. What it does demonstrate is how quickly even a relatively isolated health event can now raise questions about pandemic preparedness and economic resilience.
For gold investors, the lesson from COVID is also worth remembering. The disease itself wasn’t necessarily the catalyst for higher gold prices; it was the enormous financial response that followed. If the world were ever forced back into widespread shutdowns, another round of government borrowing, monetary support and concern over the purchasing power of currencies could again create a powerful environment for precious metals. The difference this time is that Australia would be starting with considerably more economic baggage.
Gold’s relationship with major crises is often misunderstood because uncertainty alone doesn’t guarantee higher prices. During the initial stages of COVID, investors sold almost anything they could to raise cash, and gold was caught in that rush before recovering strongly.
What eventually became important was the policy response. Governments borrowed heavily, central banks cut rates and enormous amounts of liquidity were introduced into financial markets to prevent the economic shutdown becoming a financial collapse. Those conditions reduced the relative attraction of holding cash and fixed-income assets while increasing concerns around inflation, debt and currency purchasing power.
If another major pandemic ever required a similar response, those same forces could again become supportive for gold. The important question wouldn’t simply be how serious the disease became, but how governments and central banks were forced to respond.
Disclosure: This article is provided for general information and educational purposes only and does not constitute financial advice. Markets can move quickly and past performance is not a reliable indicator of future results. Always conduct your own research and consider your personal circumstances before making investment decisions.

